
INSURANCE-FOCUSED MITIGATION
Insurance concern? Turn it into a clear property plan.
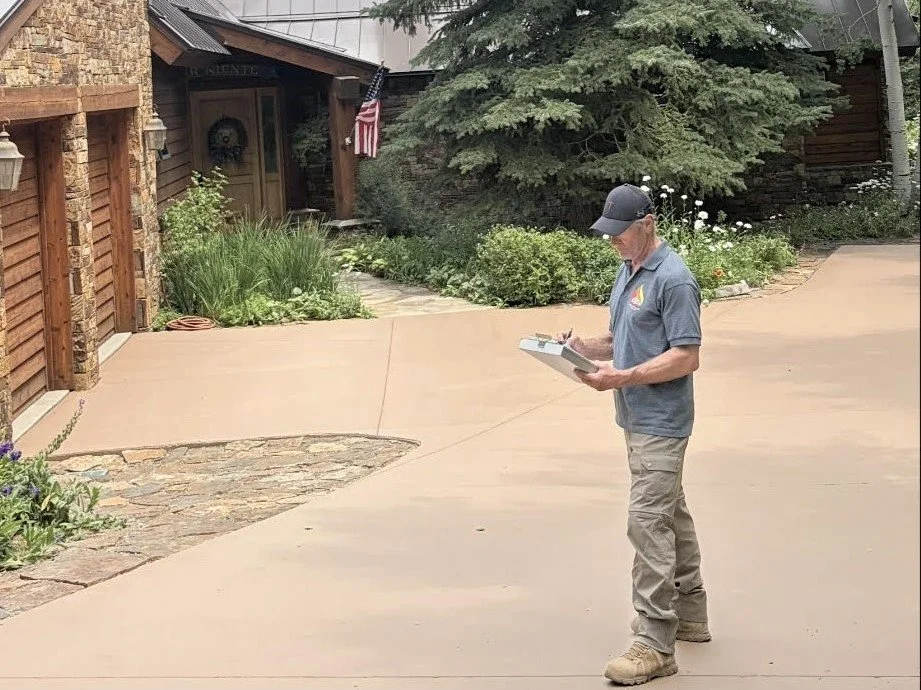
If an inspection has raised concerns or you’ve received a mitigation requirement, non-renewal notice, or a low wildfire risk score, we can help identify the issues on your property and complete the work within your control.
MITIGATION & DOCUMENTATION
How to insurance concerns into a safer home.
OUR INSURANCE RELATED WORKFLOW
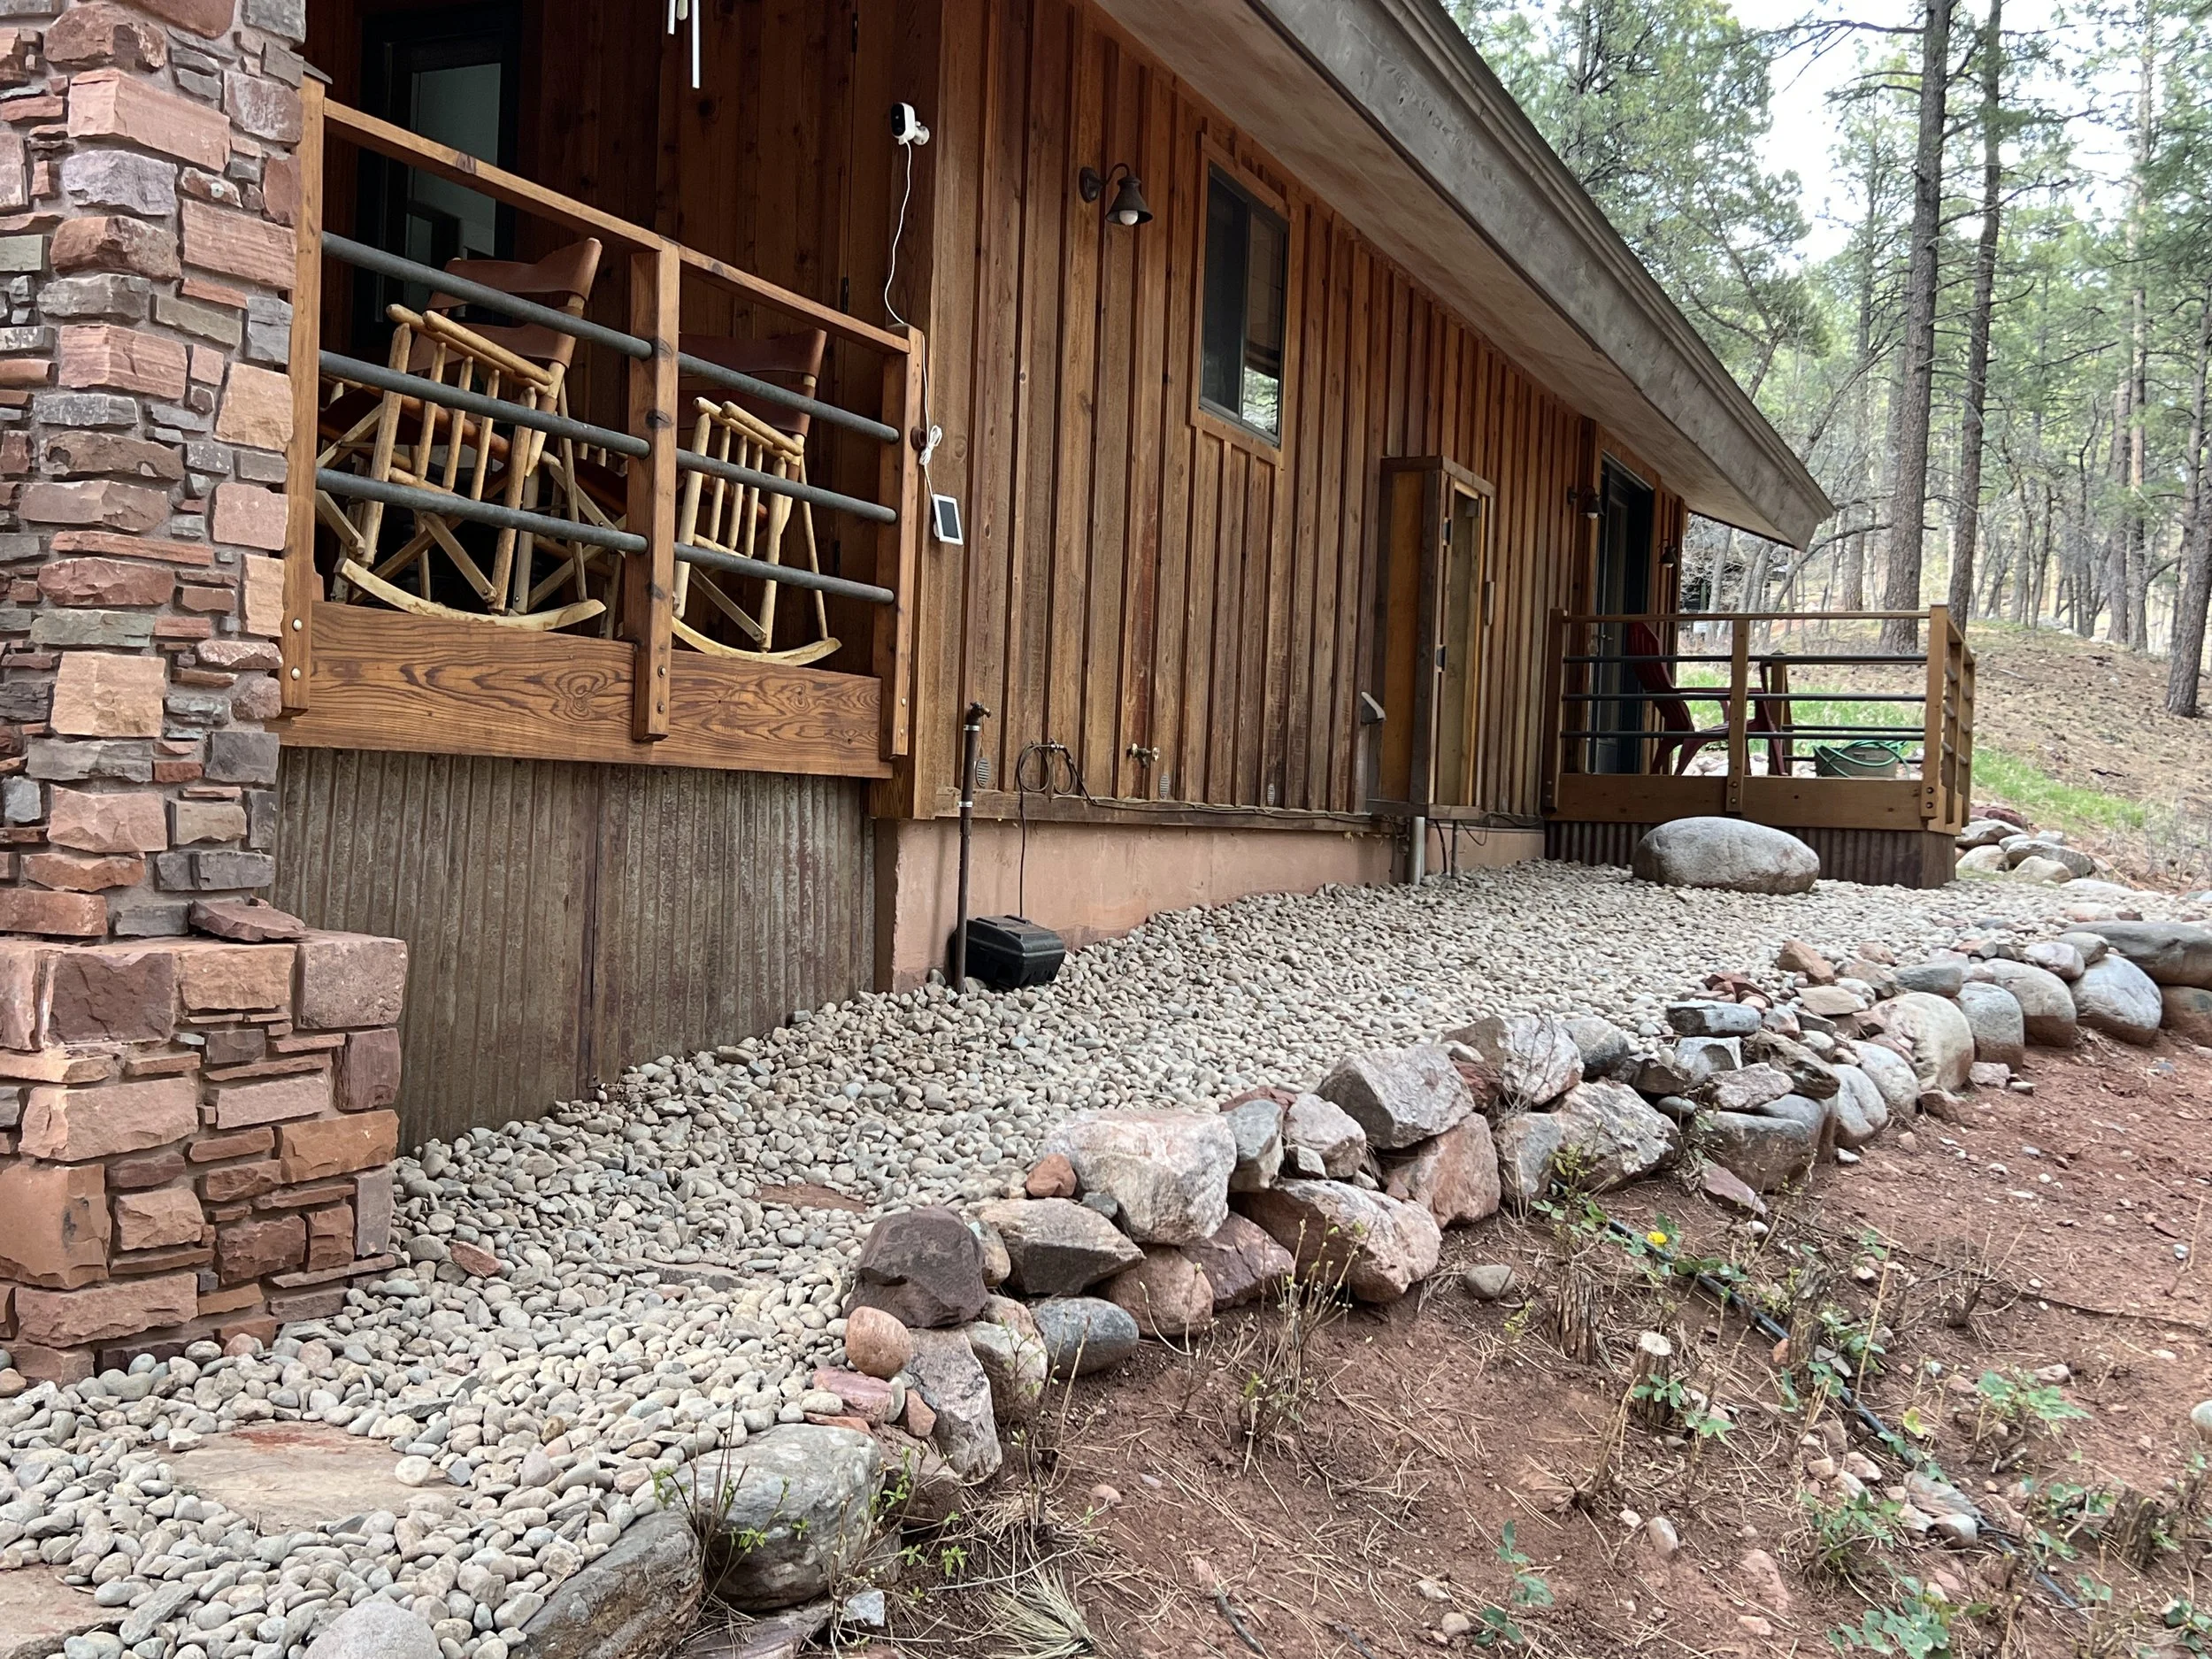
Mitigation should be understandable: What is the concern, what will addresses it, and what work was completed?
1
Send the Notice
If you have an underwriting request or concerns raised during an inspection, send it to us before the visit.
2
Site Review
We assess conditions around your home and property to determine how they relate to the concern.
3
Mitigation Scope
We recommend the work Wildfire Defense can perform and provide an estimate.
4
Completion & Documentation
We complete the scheduled work and document the completed scope where appropriate.
Mitigation now has a clearer place in wildfire-risk underwriting.
COLORADO INSURANCE CONTEXT
This new law will help protect homeowners from losing their insurance if their homes and properties meet mitigation standards. It will also help homebuyers obtain more affordable insurance if the property they plan to purchase meet those standards.
HB25-1182 became law and took effect July 1, 2026.
With the introduction of this new law, insurers are now required to recognize mitigation efforts. Insurers must account for certain property-level and community-level wildfire mitigation work when evaluating risk and pricing coverage. If their models do not account for mitigation, they generally must offer qualifying policyholders a discount for demonstrated mitigation.
Real homeowners have called us for exactly this reason.
RELEVANT CUSTOMER EXPERIENCES
★★★★★
“The work … passed all underwriting concerns.”
D. McCament — Durango
These short excerpts come from Wildfire Defense’s existing customer testimonials.
★★★★★
Wildfire mitigation for insurance was the job, and “they knew exactly what to do.”
S. Owen — Durango
★★★★★
“All mitigation work has been approved and our insurance reinstated.”
R. Post — Durango
Help us make the first conversation useful.
WHAT TO HAVE READY
If the project is tied to a deadline, include it in your form submission so we can understand the urgency.
Carrier Letter
The Non-Renewal notice from your Insurance Carrier
Deadline
The date by which your insurance carrier requires the work to be completed
Property Location
Your town or property address so we can assess travel needs and understand the property’s location.
Photos & Extra Details
Helpful if the carrier identified specific areas of concern, but not required to start the process.
Send us the situation and the date.
HAVE A CARRIER DEADLINE?
We’ll start by understanding what your insurer is asking for and what can be addressed on your property.